Trusted experts in charity and not-for-profit accounting

Kreston Reeves is committed to the charity and not-for-profit sector, recognising the important part it plays in today’s society and we are here to help support and develop it. Our wealth of experience in nonprofit accounting services has enabled us to meet the sector’s demand for specialist expertise for over 700 clients.

The sector continues to fight rising costs, funding shortages, more regulation and compliance and adverse publicity, at a time when their services are of great need. We know the current key phrases are “value for money” and “impact”. During this time of uncertainty more support is required from professional charity accountants.

SORP 2026 explained

This series of short videos breaks down the key changes under Charities SORP 2026, providing clear, practical guidance for charities preparing for the new requirements. Led by our charity experts, the videos highlight what’s changing and how to approach the updates with confidence.

You can watch them here.

Accountants and auditors for the charity and not for profit sector

We are a proactive firm of not-for-profit accountants and auditors with many years’ experience of advising charitable organisations. Kreston Reeves invests in developing our expertise and a number of the team volunteer for various charities, giving them a deeper insight into the sector.

Our long-term commitment to the charity and not for profit sector has enabled us to offer training seminars for charity trustees, and provide specialist publications to help you keep up to date with everything from the Charities Act to VAT developments affecting the sector. Areas we have covered include: Statement of Recommended Practice (SORP); public benefit; fraud; trustee responsibilities; redundancy; mergers; fund accounting; generating income – trading, property, VAT updates; employment updates- including volunteers and risk management.

We currently enjoy providing accounting services to over 700 charities and not for profit clients, including Community Interest Companies (CIC). They operate in areas including: education; care for the elderly and disabled; health and wellbeing; religion; arts, culture and heritage; Social housing; sports and the military.


The specialist charity audit and accountancy services we offer

  • Auditing the charity’s accounts and providing added value
  • Advising on governance and best practice
  • Advising on mergers, joint ventures and partnering structures
  • Advising on tax efficient fundraising and trading issues
  • VAT advice and gift aid
  • Strategic planning
  • Preparing and independently examining the charity’s accounts to ensure that they comply with best practice (SORP)
  • Advising on how best to keep the accounting records of the charity and develop financial policies
  • Secretarial duties and meeting filing requirements of the Charity Commission and Companies House (if appropriate)
Learn more about the changes of income reporting under SORP 2026

How our specialist accounting services support your charity

Working with our charity accountants team gives you access to expert financial guidance tailored specifically to the not-for-profit sector. We help you stay compliant, manage risk and make informed decisions, allowing you to free up your time and resources to focus on your mission. From navigating complex regulatory requirements to improving financial transparency for trustees and funders, our support goes beyond day-to-day accounting.

SORP 2026: Changes to revenue recognition

As a result of SORP 2026 being introduced for period commencing on or after 1 January 2026, many of our clients have been seeking further advice and guidance, which is a great example of how our charity accountants team can help you. We’ve put together a short guide which is designed to provide a high level overview of some of the key areas of the financial statements that are impacted by SORP 2026.

Discover the changes of SORP 2026 for charities and lease accounting

SORP 2026: Changes to lease accounting

Changes to lease accounting is another consideration as a result of Charities SORP 2026 being introduced, for periods commencing on or after 1 January 2026. Watch our short video to get a high level overview of some of the key areas of the financial statements that are impacted by SORP 2026.

Charity SORP 2026 accounting update webinar

We hosted a focused session chaired by charity partner Lucy Hammond with expert insights from Coral Curtis and Kimberley Foulkes. This webinar guides charities through the key changes to the Charities SORP (2026), including new accounting tiers, updated disclosure requirements, and the practical implications for reporting periods beginning on or after 1 January 2026. Designed for trustees, finance professionals and charity leaders, the session will help your organisation understand what has changed, what it means in practice, and how to prepare for the updated reporting framework.

Watch our SORP 2026 webinar on demand
Trustees annual report thumbnail

SORP 2026: Key changes to the trustees' annual report for Tier 1 charities

SORP 2026 introduces important changes to the trustees’ annual report for charities. In this short video, we explain the new Tier 1 reporting requirements, including updated disclosures on volunteers, impact reporting, reserves and financial review, helping you prepare for the revised SORP with confidence.

Whether you’re reviewing your current trustees’ annual report or planning for your next reporting cycle, this video provides a clear overview of the new disclosure requirements and highlights the areas charities should focus on to ensure their reporting is complete, transparent and aligned with the revised SORP.

In this video, we cover:

  • The new tiered reporting approach introduced by SORP 2026.
  • Changes to objectives and activities reporting, including new disclosures on volunteer contributions.
  • Enhanced impact reporting requirements and how charities can demonstrate the difference they make.
  • Updates to financial review and reserves reporting, including free reserves and going concern disclosures.
  • Requirements for future plans, governance and reference information.
  • Sustainability reporting expectations for charities under the revised SORP.
  • Practical next steps to help charities prepare for the new reporting requirements.

This is the first in a three-part video series exploring the trustees’ annual report requirements under SORP 2026, with separate videos coming soon covering the additional reporting requirements for Tier 2 and Tier 3 charities.

SORP 2026 introduces enhanced reporting requirements for Tier 2 charities, with charities expected to provide greater clarity, transparency and detail in their trustees’ annual report. In this short video, we explain the key Tier 2 requirements, including objectives and activities, impact reporting, volunteers, financial review, investments, legacy income and future plans. For charities with income of £1 million or more, the revised SORP builds on the baseline requirements that apply across all tiers, with additional expectations around the depth and detail of reporting. **In this video, we cover:** * What the Tier 2 requirements mean under SORP 2026 and how they build on the requirements for Tier 1 charities. * The distinction between ‘must’, ‘should’ and ‘may’ requirements under the revised SORP. * Changes to reporting on a charity’s short- and long-term aims and objectives. * Impact reporting, including the effects of activities on beneficiaries and wider society. * Reporting on outputs, outcomes and performance measures, including positive and negative factors affecting future plans. * New expectations around reporting general volunteers and their contribution to charitable activities. * Changes to the financial review, including principal sources of income, expenditure, risks and material investments. * New disclosure considerations for material legacy accruals and how these affect the understanding of income and future cash flows. * The requirements for reporting on future activities and how past experience can inform future plans. For Tier 2 charities, the revised SORP places greater emphasis on providing a clear picture of the charity’s objectives, activities, impact and financial position, helping readers understand not only what the charity does, but the difference it makes. This is the second in a three-part video series exploring the trustees’ annual report requirements under SORP 2026, covering Tier 1, Tier 2 and Tier 3 charities.

SORP 2026: Key changes to the trustees' annual report for Tier 2 charities

SORP 2026 introduces enhanced reporting requirements for Tier 2 charities, with charities expected to provide greater clarity, transparency and detail in their trustees’ annual report. In this short video, we explain the key Tier 2 requirements, including objectives and activities, impact reporting, volunteers, financial review, investments, legacy income and future plans.

For charities with income of £1 million or more, the revised SORP builds on the baseline requirements that apply across all tiers, with additional expectations around the depth and detail of reporting.

In this video, we cover:

  • What the Tier 2 requirements mean under SORP 2026 and how they build on the requirements for Tier 1 charities.
  • The distinction between ‘must’, ‘should’ and ‘may’ requirements under the revised SORP.
  • Changes to reporting on a charity’s short- and long-term aims and objectives.
  • Impact reporting, including the effects of activities on beneficiaries and wider society.
  • Reporting on outputs, outcomes and performance measures, including positive and negative factors affecting future plans.
  • New expectations around reporting general volunteers and their contribution to charitable activities.
  • Changes to the financial review, including principal sources of income, expenditure, risks and material investments.
  • New disclosure considerations for material legacy accruals and how these affect the understanding of income and future cash flows.
  • The requirements for reporting on future activities and how past experience can inform future plans.

For Tier 2 charities, the revised SORP places greater emphasis on providing a clear picture of the charity’s objectives, activities, impact and financial position, helping readers understand not only what the charity does, but the difference it makes.

This is the second in a three-part video series exploring the trustees’ annual report requirements under SORP 2026, covering Tier 1, Tier 2 and Tier 3 charities.
SORP 2026: Key changes to the trustees' annual report for Tier 3 charities

SORP 2026 introduces enhanced reporting requirements for Tier 3 charities, with larger charities expected to provide greater depth, transparency and evidence in their trustees’ annual report. In this short video, we explain the key Tier 3 requirements, including financial sustainability, impact reporting, ESG, volunteers and future performance.

For charities with income over £15 million, the revised SORP builds on the baseline requirements that apply across all tiers, with additional expectations around the depth and detail of reporting.

In this video, we cover:

  • What the Tier 3 requirements mean under SORP 2026 and how they differ from Tiers 1 and 2.
  • The distinction between ‘must’, ‘should’ and ‘may’ requirements.
  • Enhanced reporting on financial sustainability, going concern and financial risks.
  • Impact reporting, including outcomes for beneficiaries, wider societal impact and supporting evidence.
  • Using case studies, KPIs and performance data to demonstrate impact.
  • New expectations around environmental, social and governance (ESG) matters.
  • Greater visibility around the scale and contribution of volunteers.
  • The importance of accurate data and effective systems to support transparent reporting.

For Tier 3 charities, the revised SORP places greater emphasis on demonstrating what has changed, the impact achieved and how that impact can be evidenced.

This is the third in a three-part video series exploring the trustees’ annual report requirements under SORP 2026, covering Tier 1, Tier 2 and Tier 3 charities.
Testimonials from our charities and not for profit clients

SORP 2026 FAQs

Since the introduction of the SORP, we have received a number of questions from charities. We have brought together some of the most frequently asked questions. We hope this follow-up helps clarify key points, address common areas of uncertainty, and provide additional practical guidance. If you have a question that is not covered here, please feel free to get in touch — we always welcome further discussion. If you have any questions or would like any assistance on how the SORP will affect your charity, please get in touch.

Yes SORP 2026 is applicable for periods commencing on or after 1 January 2026, so for a March year end the first time it will be applicable will be for the year ended 31 March 2027. 

The only ‘template’ covering all of the requirements is the section of the SORP covering the Trustees Report.  When SORP 2019 was introduced model accounts were issued to assist preparers of financial statements, as well as Trustees; no such model accounts have been published yet.

No there won’t, different charities will be affected differently making it very difficult for something like this to be prepared.  Please see the comments above re model accounts. 

You may decide to over disclose in your 2026 accounts. You can early adopt but you would then have to apply the whole of SORP 2026 and not just certain elements. 

Yes, it will. Gross income is a term defined in charity law and may vary by jurisdiction.  The Charities Act 2011 defines gross income as “the gross recorded income from all sources including special trusts. For accounts prepared on an accruals basis, gross income is the total incoming resources as shown in the Statement of Financial Activities (prepared in accordance with the SORP) for all funds but excluding the receipt of any endowment and including any amount transferred to income funds during the year from endowment funds in order to be available for spending”.

No. The only investments to be excluded from the free reserve calculation are those made specifically for achieving the charity’s purpose and are accounted for as social investments. Treasury deposits are held to generate a financial return.

No not necessarily, each contract will need to be reviewed and considered separately. 

The basic answer is no; there is not.  We appreciate that this can distort the figures in the year when there is a significant one-off legacy recognised, but that is how it needs to be accounted for.  This is where the narrative reporting is so important and why SORP 2026, for tier 2 and 3 charities, includes a requirement to include narrative in the Trustees Annual Report about material legacies that have been accrued so that the users of the financial statements can gain more of an understanding around the charity’s cashflows. 

Turnover linked payments of rent are excluded from the lease liability under FRS 102, as they are under IFRS 16. Variable lease payments are only built into the liability when they’re linked to a rate or index (like CPI or RPI). That’s not the case when rent is linked to turnover.

If the lease states that the rental cost will increase in line with a rate or index, such as CPI or RPI, then the amounts for future years should be estimated using the index or rate at the commencement date. However, if there is also a break clause at the time of the rent review, then it will be necessary to consider whether the charity is reasonably certain to exercise that option or not. If the charity expects to continue with the lease, then the full period of rental costs should be used to calculate the initial ROU asset and lease liability.

The SORP sets out that the decision to award a grant may create a funding commitment, this is recognised as a liability when the recognition criteria have been met:

  • the criteria for an obligation are met; 
  • payment of the grant is probable; 
  • the liability can be measured reliably (which for approved grants is straight forward); and 
  • there are no performance-related conditions that limit the recognition.

Where you approve a multi-year grant that is subject to performance-related conditions (or the donor charity may be able to legitimately withdraw from its commitment) the recognition of a liability is not required. The SORP clearly states “Provided the performance-related condition and review process has been communicated to the recipient as part of the funding agreement and the review process has substance (i.e. the review has a potential impact on future payments), then the criteria for recognition of a liability are unlikely to be met.”  Equally if there are no performance-related conditions attached to a grant that allows the done charity to realistically avoid the commitment, a liability for the full funding should be recognised (if this funding was for a number of years then you would also have to consider, if material, the time value of money and discounting the liability to the present value).

If you are providing a grant, the payment of which is dependent on say matched funding, the matched element is outside of your control.  In this situation, a liability arises and the expenditure must be recognised, if the payment of the grant is probable.

Where you have funding commitments, so future grant payments that are considered to be possible, these should be disclosed as a contingent liability, and the note should explain how these unrecognised funding commitments will be funded (this element is a new disclosure requirement). 

Kreston Reeves has made every effort to ensure accuracy at the time of publication (May 2026). Information may be subject to legislative changes. Recipients should note that information may not reflect individual circumstances and should, therefore, not act on any information without seeking professional advice. We cannot accept any liability for actions taken or not taken as a result of the information given in this factsheet. Kreston Reeves LLP (registered number OC328775), Kreston Reeves Audit LLP (registered number OC306454) and Kreston Reeves Private Client LLP (registered number OC342713) operate under the Kreston Reeves Brand and are together known as “Kreston Reeves”. Any reference in this communication or its attachments to “Kreston Reeves” is to be construed as a reference to the Kreston Reeves entity from which the information originates. All entities are registered in England and Wales, and the registered office address is 2nd Floor 168 Shoreditch High Street, London E1 6RA. Further details can be found on our website at www.krestonreeves.com.

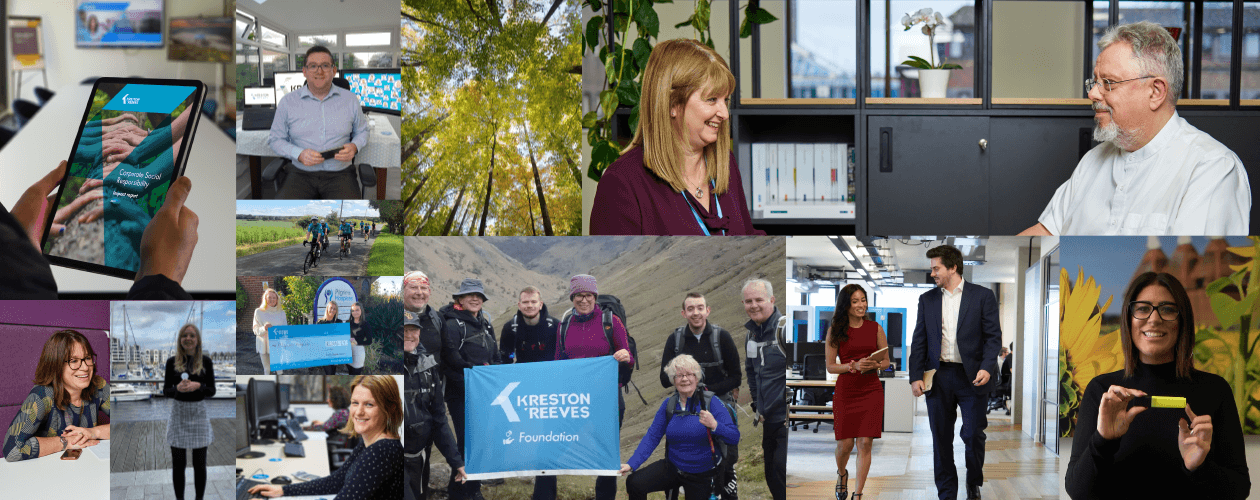
A series of photos demonstrating the Kreston Reeves purpose, in office, charity challenge and candid photos.

Our purpose, our passion

To guide our clients, colleagues and communities to a brighter future.

In a continually evolving world we help all generations embrace change through trusted advice, support and guidance. Our passion for continued improvement ensures that we work to understand your goals, support and advise you on your journey and help you to realise your ambitions.

About us

Leading our charities and not for profit team

We have offices throughout London, Kent and Sussex with people from across all of our service delivery teams. Where ever you are located, our experts will be able to help provide the services you need to achieve your goals and objectives. Don't forget to subscribe to our newsletter below to stay up to date with all of our latest news and insights. You can also follow us on social media using the links below.

Sam Rouse

Sam Rouse FCCA DChA

Audit Partner and Head of Charities and Not for Profit

Email Sam

    • yes I have read the privacy notice and am happy for Kreston Reeves to use my information


    Lucy Hammond

    Lucy Hammond FCA DChA

    Audit Partner

    Email Lucy

      • yes I have read the privacy notice and am happy for Kreston Reeves to use my information


      Kimberley Foulkes

      Kimberley Foulkes FCCA

      Audit Senior Manager

      Email Kimberley

        • yes I have read the privacy notice and am happy for Kreston Reeves to use my information


        Coral Curtis

        Coral Curtis BSc (Hons) FCA

        Audit Senior Manager

        Email Coral

          • yes I have read the privacy notice and am happy for Kreston Reeves to use my information